Motor Insurance in India: What Vehicle Owners Should Know
Understand motor insurance in India, including third-party and comprehensive coverage, add-ons, premiums, NCB, claims and important points to check before renewal. Learn about motor insurance in India, including third-party cover, comprehensive policies, add-ons, premiums, No Claim Bonus and vehicle insurance renewal tips.
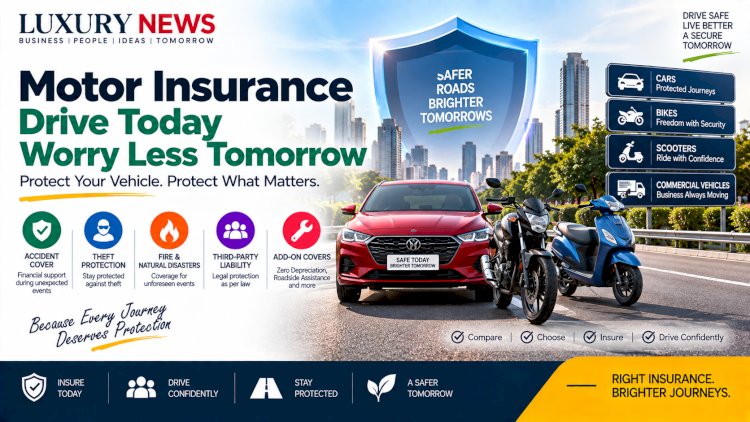
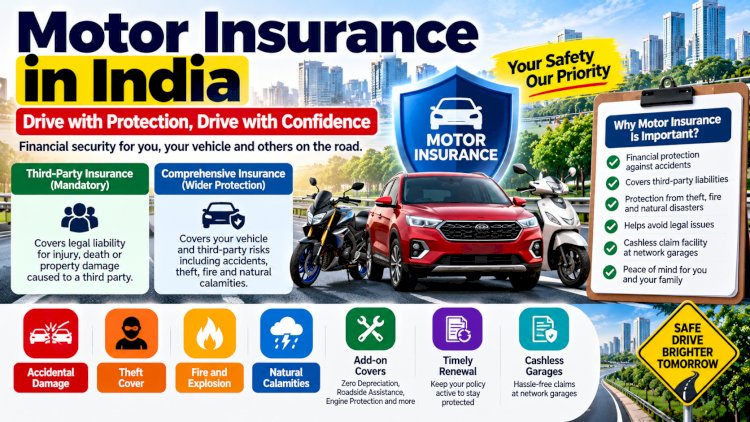
Motor insurance is an important part of vehicle ownership in India. It provides financial protection against certain losses arising from accidents, theft, natural events and third-party liabilities, depending on the policy selected.
Whether you own a car, motorcycle or scooter, understanding the different types of motor insurance can help you choose coverage that matches your vehicle and requirements.
What Is Motor Insurance?
Motor insurance is a contract between the vehicle owner and an insurance company. In return for the premium paid by the policyholder, the insurer provides coverage for specified risks and losses according to the terms, conditions and exclusions of the policy.
Motor insurance generally covers two broad areas: third-party liability and damage to the insured vehicle.
Third-Party Insurance
Third-party liability insurance provides coverage for certain legal liabilities arising from injury, death or property damage caused to a third party through the insured vehicle, subject to the applicable policy terms and law.
Third-party motor insurance is a legal requirement for vehicles using public roads in India.
However, third-party cover does not generally pay for damage to the policyholder's own vehicle.
Comprehensive Motor Insurance
A comprehensive policy can combine third-party liability protection with coverage for damage to the insured vehicle, subject to the policy terms.
Depending on the policy, own-damage coverage may respond to risks such as:
- Road accidents
- Theft
- Fire
- Natural disasters
- Certain man-made events
- Other specified risks
The exact coverage varies between insurance products.
Own-Damage Insurance
Vehicle owners who already have the required third-party cover may also consider a standalone own-damage policy for protection against damage to their own vehicle.
The suitability of this option depends on the vehicle owner's existing insurance coverage and individual requirements.
No Claim Bonus
Policyholders who do not make certain claims during eligible policy periods may qualify for a No Claim Bonus (NCB) on the own-damage premium, subject to applicable rules and policy conditions.
NCB is linked to the policyholder's claim-free record and can be an important factor when renewing motor insurance.
Motor Insurance Is More Than a Renewal Requirement
For vehicle owners, insurance is not simply an annual renewal exercise. The right coverage can help manage the financial consequences of unexpected incidents while also meeting mandatory legal requirements.
Before buying a policy, customers should compare the coverage, exclusions, deductibles, IDV, add-ons and claim services and select a product appropriate to their needs.
Need Help With Motor Insurance?
Sameer Shaik Ali
Insurance Advisor
???? Phone: 9686604488
For motor insurance assistance, policy renewal and related insurance requirements, contact Sameer Shaik Ali – Insurance Advisor.